A construction site can be busy, appear to be on schedule and still lose margin at the same time.
This happens when the estimate stays in the office while quantities, timelines, crews, supplies and the sequence of work change in the field.
The problem often emerges too late: when supplier invoices arrive, when the final cost report is prepared or when the owner discovers that a phase that cost far more than expected has already been completed.
That is why construction cost control should not be considered an accounting check performed at the end of the project.
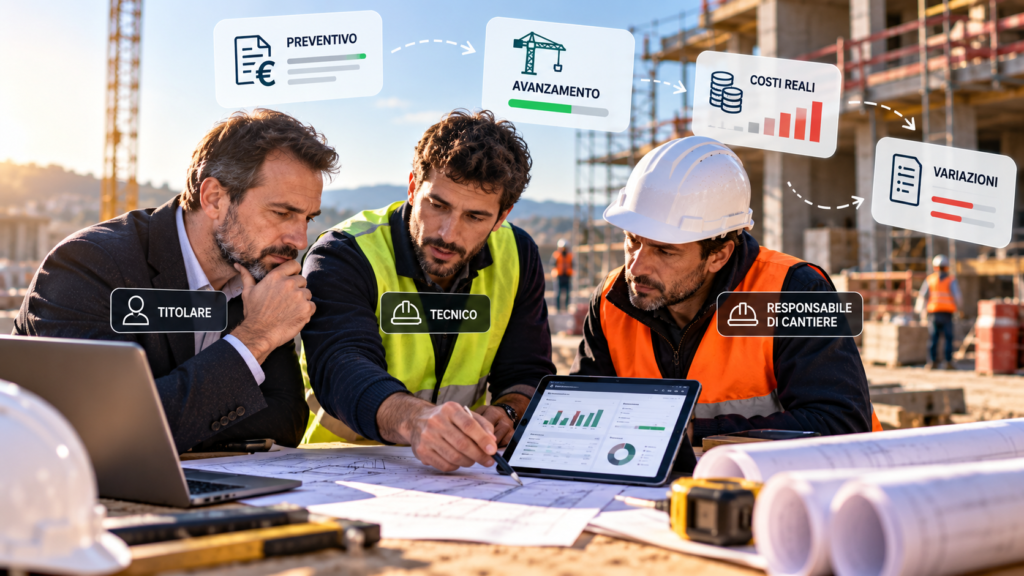
It is an ongoing workflow that connects three different viewpoints:
- the owner, who must understand where the margin is under pressure and make decisions;
- the technical professional, who translates quantities, phases and changes into financial impacts;
- the site manager, who is the first to see what is actually happening in the field.
If these three people work from different information, financial control always comes after the event.
If, instead, there is a simple, repeatable cycle, the estimate stops being a static document and becomes a reference that can be used throughout the project.
Cost control does not start with the final cost report
Let’s imagine a construction site that finishes with a margin below expectations.
When we analyze the final cost report, we discover that one phase required more hours, some materials cost more than expected and two additional work items were completed without immediately updating the financial picture.
At the end of the project, we can explain exactly what happened.
But by then, there is little we can do to correct it.
True control means recognizing the variance while it is still possible to act.
The workflow should therefore connect:
Estimate → Orders → Execution → Progress → Changes → Comparison → Decision → Final cost report
Each step produces information that can change the financial forecast.
The RICS Construction Productivity Report 2026 shows how fragmented the industry still is, including in the way it measures productivity.
One of the most widely used metrics is earned value compared with actual cost: in other words, relating the value of the work actually completed to what was spent to deliver it.
The principle is exactly what a small or medium-sized business also needs: do not look only at how much you spent, but at how much work you actually obtained from that spending.
An estimate can be controlled only if it was built for that purpose
If the estimate contains only a total price, it will be difficult during construction to understand where the variance originated.
A more useful structure should link costs at least to the main phases or work categories.
For example:
- demolition;
- structural work;
- masonry;
- building systems;
- finishes;
- rentals;
- subcontracting;
- indirect costs attributable to the project.
There is no need to build hundreds of line items.
What is needed is enough detail to understand, during execution, where the actual result is moving away from the initial assumption.
For each phase, the following may be useful:
- planned quantities;
- planned material costs;
- planned hours or days;
- any suppliers and subcontractors;
- reference financial amount;
- main assumptions used in the estimate.
This last element is often forgotten.
If we built the price assuming a crew of four people for five days, that assumption should also be recognizable during the work.
When it becomes seven days, the technical professional can immediately understand that something has changed.
Owner, technical professional and site manager: three different questions about the same data
An effective workflow does not require everyone to do everything.
It requires each person to receive the information needed to make their own decision.
The site manager: what happened?
This is the person closest to execution and the first to identify:
- a different quantity;
- unusual consumption;
- a crew taking longer than expected;
- additional work;
- a delivery that changes the schedule;
- a problem that could generate additional costs.
Their job should not be to perform a complete financial analysis.
They must be able to quickly record the event that could have a financial impact.
The technical professional: why did it happen?
The technical professional turns the operational data into an assessment.
If a quantity increases, they must determine whether it results from a design change, an inaccurate initial estimate, a different execution method or a recording error.
This is where the estimate and reality begin to interact.
The owner: what should we do?
The owner should receive information that is sufficiently summarized to decide:
- can we absorb the variance?
- do we need to revise the schedule?
- do we need to negotiate with the client?
- would it be better to change suppliers?
- do we need to increase or reduce resources?
- is the expected margin still realistic?
The advantage of this structure is that the same information does not have to be interpreted from scratch three times.
What information must actually come from the construction site
Financial control fails when it requires the person in the field to become an accountant.
The data collected should be limited and genuinely usable.
Depending on the project, it may include:
- phase or activity concerned;
- progress status;
- hours or days used;
- any significant quantities;
- unusual materials or supplies;
- requested changes;
- problems that could generate a cost;
- photos or documents useful for reconstructing the event.
The quality of control depends on data continuity, not quantity.
A 50-field report completed poorly once a month may be less useful than five reliable pieces of information collected regularly.
The weekly cycle: from the construction site to the decision
For many small and medium-sized businesses, a weekly review can be a good compromise between control and administrative workload.
The RICS 2026 data also shows how variable measurement frequency remains across the industry: monthly control is still the most common in many regions, while weekly measurement is significantly less widespread.
Waiting for the monthly financial cycle, however, may be too slow for some operational decisions.
A weekly workflow could work as follows:
1. Site manager
Updates the status of the main phases, unusual events, changes and necessary information.
2. Technical professional
Compares what happened with the planned quantities, timelines and assumptions and identifies significant variances.
3. Owner
Receives a financial summary and decides which variances require action.
4. System
Relevant decisions remain linked to the project and become the new reference for the next review.
There is no need to discuss every estimate line item every Friday.
Attention should be focused on exceptions.
The most expensive phrase on a construction site: “let’s just do it for now”
Many variances do not originate from calculation errors.
They originate from small changes carried out without immediately updating the financial picture.
The client requests a different finish.
A work item is extended.
A different material is needed.
In the field, the change may seem simple. Financially, it may not be.
For every significant change, it is advisable to record at least:
- what changed;
- who requested the change;
- when it was requested;
- which work items it affects;
- estimated effect on materials, hours and time;
- decision made;
- any approval required under the applicable contract.
There is no universal percentage threshold above which the owner must intervene.
Each company can set internal thresholds consistent with its size, structure, margin and project type.
You do not need 40 KPIs: you need the ones that change a decision
The risk with dashboards is measuring everything and controlling little.
For an initial implementation, a few indicators may be enough:
- planned budget by phase;
- costs actually recorded;
- phase progress percentage;
- variance between planned and recorded;
- planned hours or days compared with those used;
- value of changes still awaiting approval or valuation;
- updated estimate of cost at completion.
The last indicator is particularly important.
Knowing that we have exceeded an item by $2,000 today is useful.
Understanding that, if the same trend continues, we could finish the phase with an additional $8,000 in costs is much more useful for decision-making.
Three scenarios showing how the workflow works
Scenario 1 — The material is being consumed faster than expected
The site manager reports the data.
The technical professional checks whether the problem comes from the initial quantities, installation method, waste or another cause.
The owner decides only once the financial effect is known.
The value of the workflow is not to “solve the problem automatically.” It is to prevent the problem from remaining invisible.
Scenario 2 — The client requests a change
The request is recorded before it simply becomes part of the ordinary work.
The technical professional assesses its effect and the company applies the approval process required by the contract.
The internal budget is updated only on the basis of the decision actually made.
Scenario 3 — A phase falls behind schedule
The cost is not necessarily limited to the crew involved.
The delay may shift a rental, change a subcontractor’s start date or extend certain indirect costs.
The workflow makes it possible to see the overall effect before it becomes the final cost report.
Six errors that cause loss of margin control
1. Checking only at the end of the month
Some operational decisions cannot wait for the monthly administrative cycle.
2. Comparing only planned spending with actual spending
You must also consider how much work was completed with that spending.
3. Not linking changes to the budget
The budget continues to appear correct while the actual project has already changed.
4. Using different files for each role
If the owner, technical professional and site team use different figures, every meeting begins by reconciling the data.
5. Asking the person in the field for too much data
An overly burdensome process will be completed poorly or abandoned.
6. Not using the final cost report to improve the next estimate
The project just completed should make tomorrow’s estimate more accurate.
In 2026, the problem is not having software: it is having usable data
Digitalization in the industry is already highly advanced in several areas.
The study Deloitte Access Economics / Autodesk — State of Digital Adoption in the Construction Industry 2026 analyzed 954 construction and engineering companies in six Asia-Pacific markets.
Fifty percent use cloud construction management software, 56% use data analytics and 47% use mobile applications.
Yet the report emphasizes that greater use of technology does not automatically produce better performance.
Interoperability, data quality and internal skills remain challenges, while the median number of systems and point solutions used by the companies surveyed is still six.
For cost control, this means that having one software tool for budgeting and another for the construction site does not automatically solve the problem.
The question is: how quickly can an event that occurs in the field become usable information for a financial decision?
Technology does not replace management discipline
The McKinsey Executive’s Survival Guide to Capital Projects, 2026 highlights a familiar risk in complex projects: the illusion of having everything under control because dashboards and updates continue to show an apparently positive situation.
The principle is also valid on a much smaller scale.
A green dashboard is worth little if the data arrives late.
A good workflow should therefore prioritize:
- data quality;
- appropriate frequency;
- clear responsibilities;
- the ability to act when a variance emerges.
A four-week test before changing the entire company
Week 1 — Map the process
Choose a construction site and observe how costs, changes and progress are actually recorded.
Identify how many files exist and who updates what.
Week 2 — Connect the phases
Build a simple correspondence between the main financial items and operational phases.
Week 3 — Activate the weekly cycle
Site manager → technical professional → owner.
Focus only on variances requiring attention.
Week 4 — Evaluate the result
Ask yourself:
- did we identify variances earlier?
- did we spend less time reconstructing the data?
- are changes more visible?
- does the owner have better information for making decisions?
- does the site manager consider the process sustainable?
Only after this test is it worth applying the method to the other projects.
Where Edil-Up can help with construction site cost control
Edil-Up is developed as a Construction Operating System with the aim of progressively connecting information that is often managed in separate environments within a company.
Within construction site management, a company can organize sites, phases, collaborators, documents, communications, roles and permissions, attendance and basic financial information.
For cost control, the value lies above all in context.
A phase, document, communication or project-related piece of information does not necessarily have to live in a completely separate place.
This can help the owner, technical professional and site manager start from the same operational reference.
Edil-Up does not replace specialist accounting, quantity surveying or cost management software when a company needs advanced dedicated features.
The goal is to reduce the distance between what happens on the construction site and the information the company uses to manage it.
For more information, you can also consult the guide dedicated to cost, estimate and budget control and the comparison of construction site management software.
Checklist for the next construction site meeting
- Which three phases have the greatest financial impact?
- Is the initial budget divided so they can be controlled?
- What data must the site manager provide?
- Who analyzes the variances?
- Who decides on the corrective action?
- Do open changes already have a financial estimate?
- Do we know the estimated cost at completion?
- Are we comparing cost and progress, or only invoices?
- Will the decisions made this week remain traceable three months from now?
International reference sources
- RICS — Construction Productivity Report 2026, international research on productivity measurement, control frequency, scheduling, coordination and site management.
- RICS — New Rules of Measurement, an international framework for estimating, cost planning and cost information management.
- Deloitte Access Economics / Autodesk — State of Digital Adoption in the Construction Industry 2026, an analysis of the digital maturity of 954 construction and engineering companies.
- McKinsey & Company — An executive’s survival guide to capital projects, 2026, an analysis of governance and control in large, complex projects.
Conclusion: margin is not controlled at the end of the construction site
The estimate establishes an assumption.
The construction site continually tests it.
Cost control helps determine early enough when the two begin to diverge.
It does not necessarily require complex dashboards, dozens of KPIs or daily meetings.
Above all, it requires a clear flow:
the site manager records what changes, the technical professional understands its effect and the owner decides what to do.
When this sequence works, the final cost report should no longer tell an entirely new story.
It should be the final confirmation of information the company has already used to manage the project during execution.
Margin is lost during construction. That is when it must be protected.
The Edil-Up team